The Cost of Rebuilding After a Wildfire vs. Installing a Frontline System.
Rebuilding after a wildfire isn’t just about replacing your roof and walls. It involves navigating supply chain surges, prolonged displacement, and compounding out-of-pocket expenses. When evaluating wildfire defense, you’re comparing a predictable, one-time investment in active protection against the staggering, uncertain cost of starting over.
Here’s a breakdown of the true financial reality of post-fire reconstruction vs. installing an automated Frontline Wildfire Defense System.
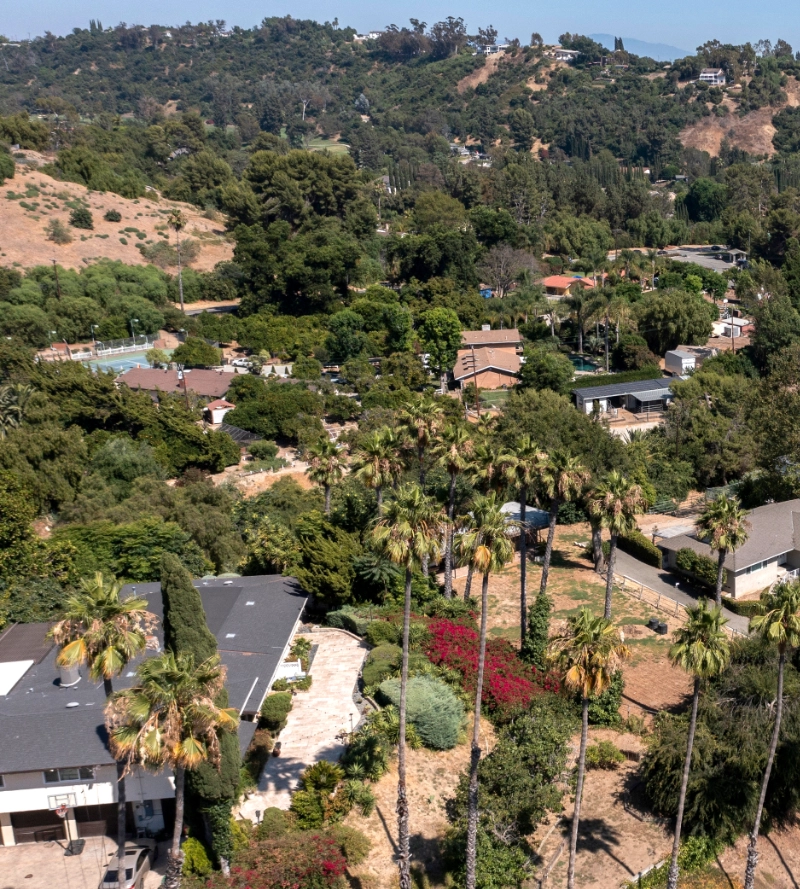
The financial reality of rebuilding after a wildfire.
When a wildfire impacts an entire community, the normal market rules collapse. Post-disaster recovery creates demand spikes because contractors, skilled trades, and basic building materials are in short supply. Combined with infrastructure damage and permitting backlogs, the cost of rebuilding your home after a wildfire far exceeds standard construction estimates, especially in wildland-urban interface (WUI) zones.
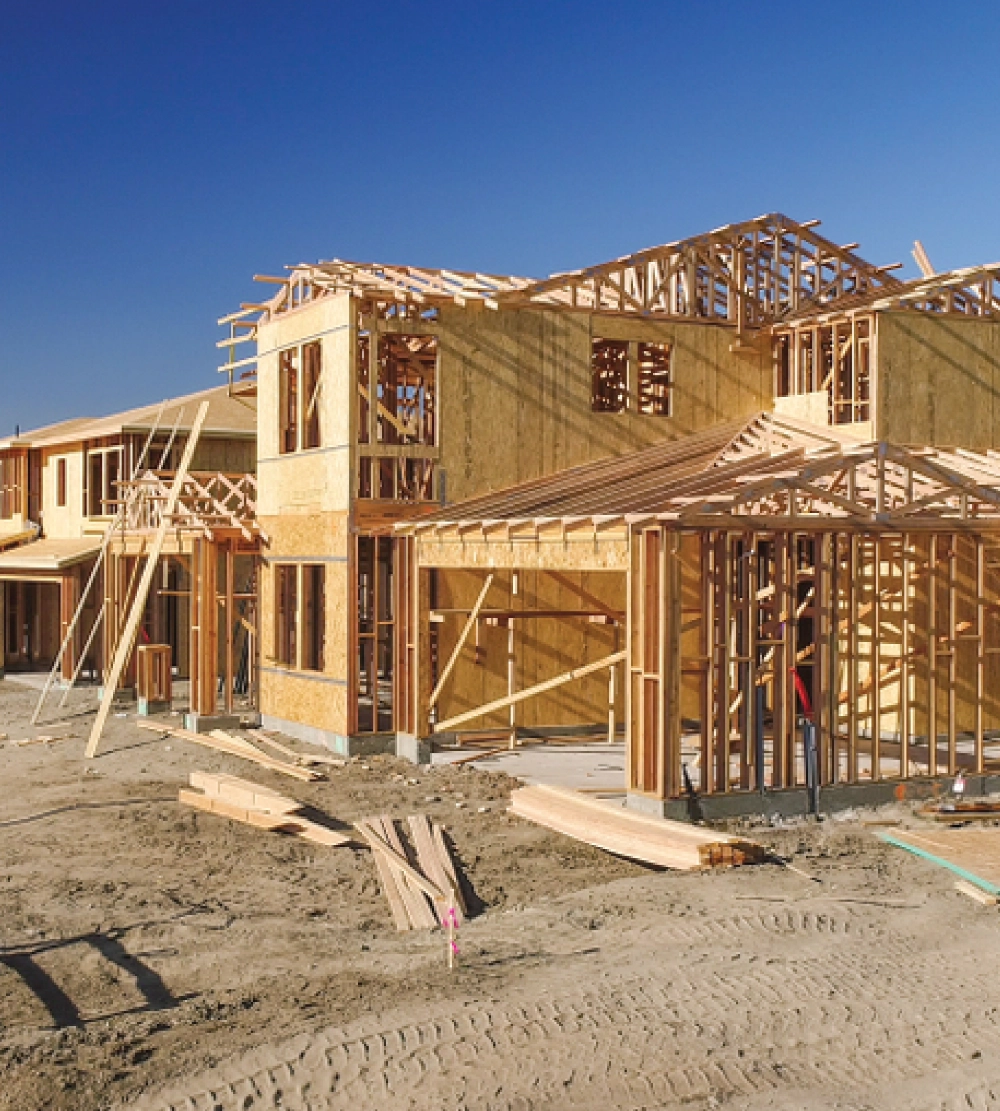
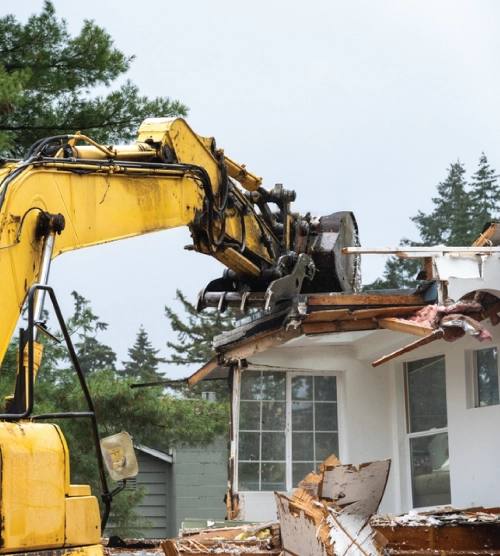
Debris Removal & Site Remediation.
Remove structural ash, hazardous waste, and heavy soil contamination before construction can begin. Post-fire runoff frequently causes slope instability, requiring remediation to prevent landscapes from collapsing.
Cost estimate:
$5,000-$115,000 or more
Sources: Oregon Department of Environmental Quality and California Department of Insurance
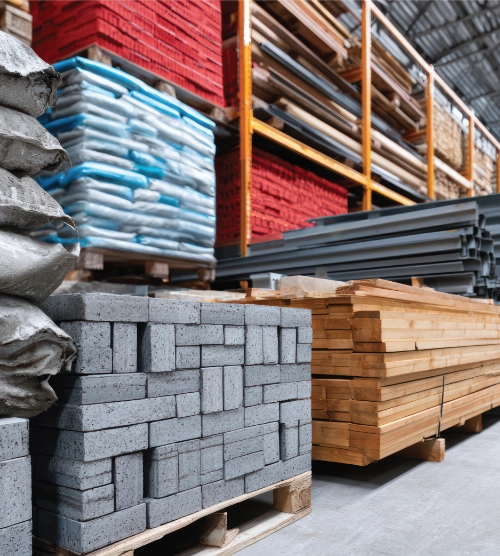
Price Spikes On Labor & Materials.
Regional destruction creates intense competition for contractors, skilled trades, and building materials, driving post-disaster prices higher. In recent Los Angeles wildfire rebuilds, costs have reached $800–$3,000 per square foot, with costs in high-end markets like Jackson Hole and Aspen reaching even higher.
Cost estimate:
$800-$3,000+ per square foot
Source: Los Angeles Times; Aspen Times
Mandatory Building Code Upgrades.
When you rebuild, local laws force you to meet the latest fire-safety codes. These modern upgrades can add thousands to construction costs, and standard insurance policies rarely cover the full bill.
Cost estimate:
$13,000-$28,000
Temporary Housing & Living Expenses.
Rebuilding typically takes 18 to 36 months. During that time, you’ll need to pay for temporary housing and living expenses. These costs tend to rise as others in your community compete for available housing. You may also exceed your policy limits before your rebuild is finished.
Cost estimate:
$72,000-$180,000
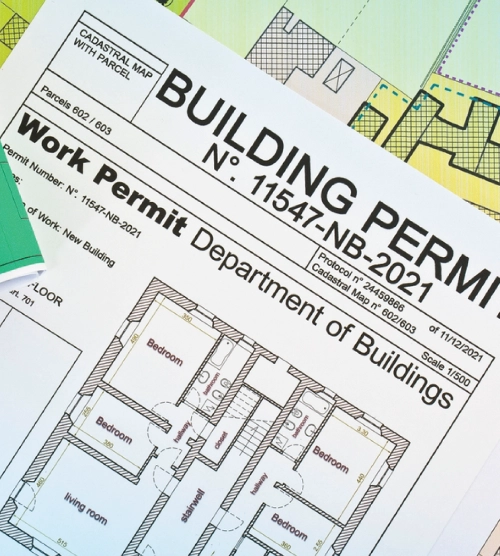
Permits & Inspection Fees.
Before your rebuild can begin, you have to pay the city or county for building permits, design reviews, and safety inspections. These administrative fees add up fast.
Cost estimate:
$17,700-$30,900
Source: Los Angeles County
Landscape & Site Restoration.
Beyond rebuilding your house, you’ll need to replace your driveways, landscaping features, and retaining walls and fences. Insurance coverage varies by policy, as do coverage limits.
Cost estimate:
$10,000-$50,000
Uninsured Policy Gaps & Deductibles.
Many homeowners find they’re underinsured, and their payouts fail to cover their full expenses. It’s common for insurance payouts to fall 20% short of the actual costs to rebuild, leaving you with large out-of-pocket bills.
Cost estimate:
$100,000-$300,000
Source: California Legislature
Extended Rebuilding Timelines.
Every day of delay in rebuilding increases your costs. Paying a monthly mortgage on a home you can’t live in while also covering a temporary place to stay can quickly drain your savings and insurance payouts.
Cost estimate:
$72,000-$180,000
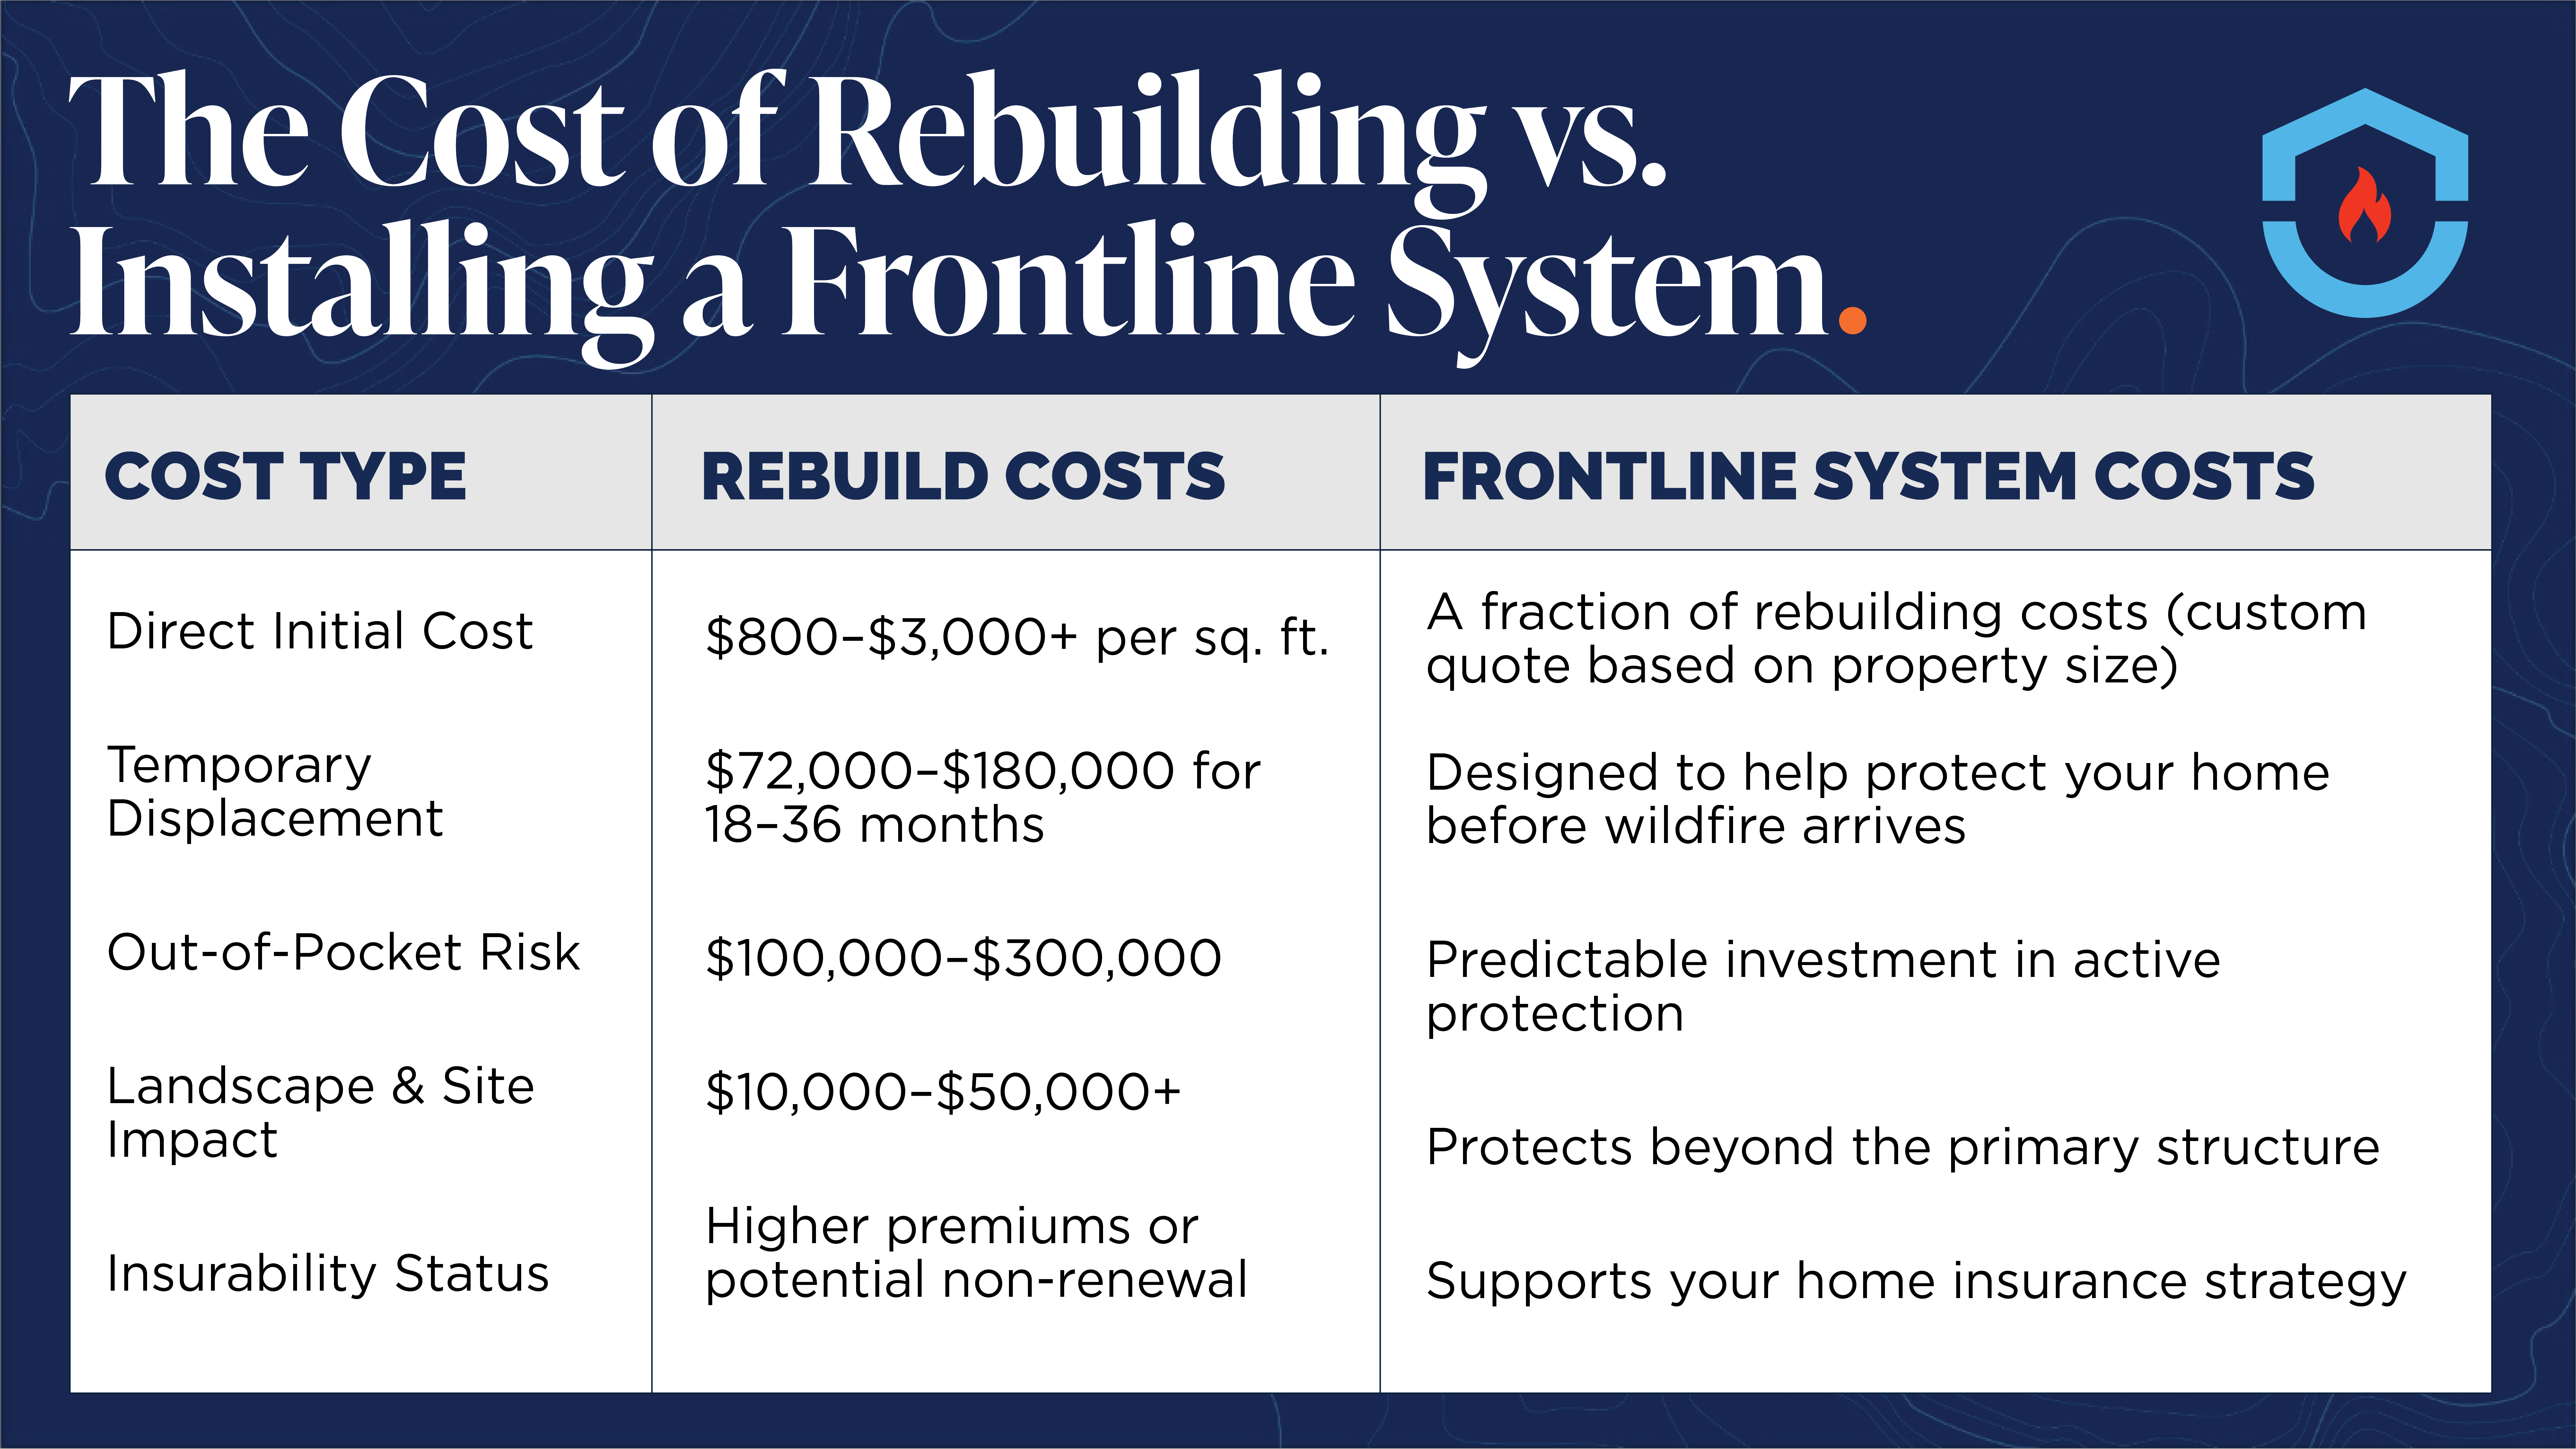
Comparing the costs of rebuilding a home vs. installing a Frontline system.
Rebuilding after a wildfire comes with unpredictable, compounding expenses and financial risk. In fire-affected regions, labor shortages, material spikes, and permitting queues can sharply drive up construction costs. Recent Los Angeles wildfire rebuild estimates reached $800–$1,000+ per square foot, while construction costs in high-cost markets like Aspen can reach $3,000 per square foot or more.
Installing an automated wildfire defense system minimizes that risk. Your home is where your family lives and where your life happens, and much of what’s inside can never be replaced by an insurance check. Instead of risking years away from home, exhausting contractor bids, and unexpected out-of-pocket costs, Frontline offers a clear, predictable way to protect what matters most before a fire ever gets close.
“Most people still think of wildfire in terms of what it costs to rebuild a house. What they often overlook is the years of displacement, the disruption to their lives, and the meaningful pieces lost within the home. The most expensive part of a wildfire is rarely the structure alone.”
— Harry Statter, Founder & CEO
Offsetting the cost of a proactive wildfire defense system.
Installing a Frontline Wildfire Defense System is an investment in active protection. By combining real-time satellite intelligence with automated exterior sprinklers and Class-A firefighting foam, Frontline prevents ember ignition before structures catch fire. You aren’t just shielding four walls; you’re preserving your property’s equity, surrounding landscape, and assets that insurance could never replace.
REDUCE THE RISK OF COSTLY WILDFIRE DAMAGE.
Frontline combines proprietary wildfire intelligence with automated hardware that activates before flames get close. Powered by official agency fire data, real-time satellite heat detection, and wildfire camera networks, the system monitors fire activity and can automatically* activate when an active wildfire is within about 7 miles of your property coincides with high-risk weather conditions.
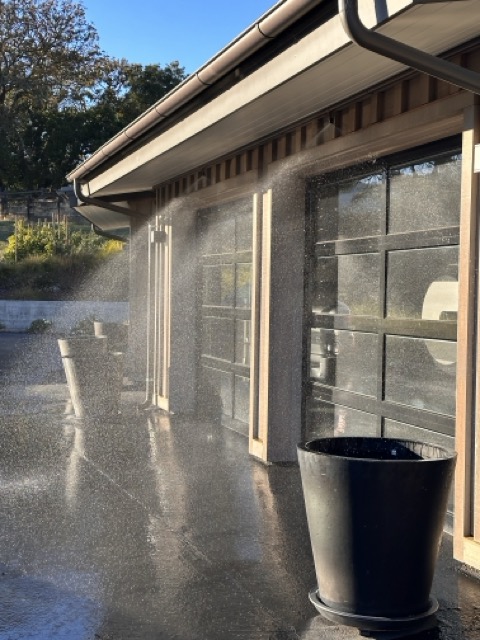
Strategically placed eave and roof sprinklers saturate vulnerable ignition points with a mixture of water and biodegradable Class-A firefighting foam to reduce ember ignition risk, which is the primary cause of structure loss in wildfires.
“The reality is that our emergency response system is under increasing strain. Today’s wildfires move faster, burn larger, and spread embers miles ahead of the flame front. When hundreds or even thousands of homes are threatened at once, firefighters have to prioritize saving lives. That’s why homes increasingly need the ability to defend themselves.”
— Harry Statter, Founder & CEO
PROTECT LANDSCAPING AND PROPERTY FEATURES THAT ARE DIFFICULT TO REPLACE.
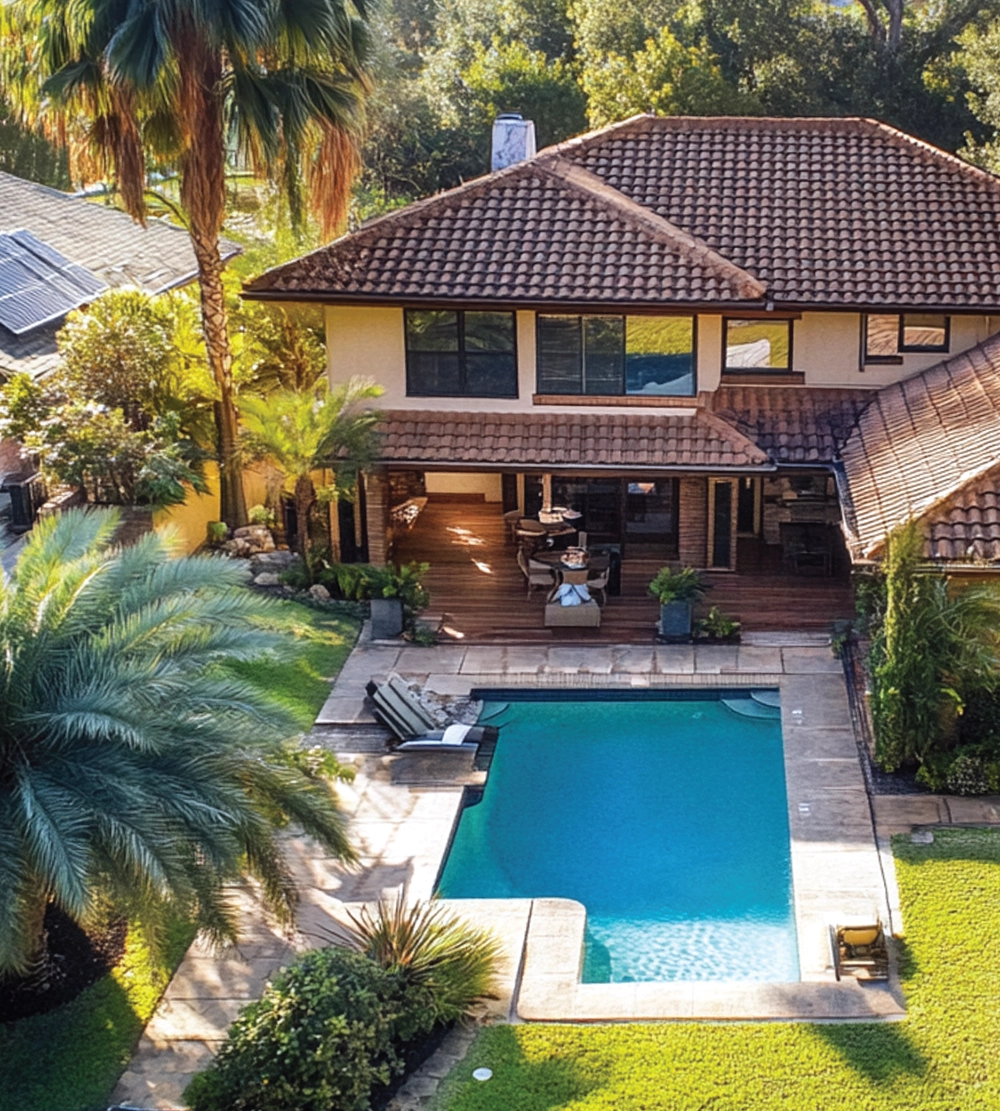
A wildfire destroys more than buildings. It strips mature trees, custom hardscaping, and natural soil stability that take decades to establish. After a fire, property owners often face massive out-of-pocket costs for site clearing, soil remediation, and slope stabilization before rebuilding can even begin. Active wildfire defense preserves the surrounding landscape, protecting property value and eliminating costly post-fire remediation.
SHIELD VULNERABLE NON-ATTACHED COMBUSTIBLES.
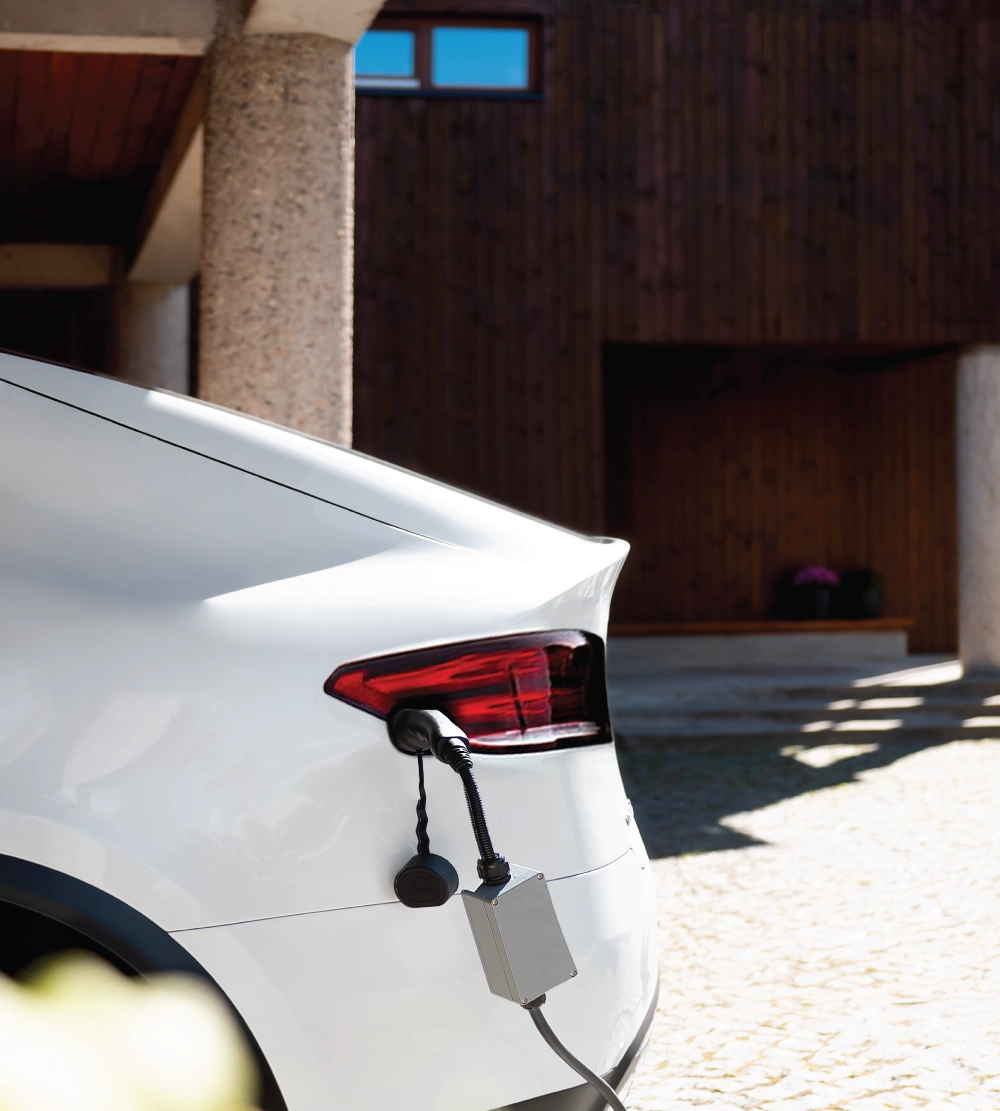
Standard rooftop sprinklers leave critical areas exposed. Wildfire embers frequently land on non-attached combustibles, such as wooden decks, fences, outdoor furniture, electric vehicles, charging stations, and detached structures, igniting localized fires that spread to the main home.
The Frontline system extends automated defense up to 30 feet beyond the primary structure. Using precision eave sprays and perimeter coverage, the system coats surrounding high-risk surfaces with water and non-toxic, biodegradable Class-A foam, maintaining moisture barriers in extreme winds and stopping ignition at the perimeter.
SUPPORT YOUR HOME INSURANCE STRATEGY.
The expanding wildfire crisis has led to widespread non-renewals and increased premiums in WUI communities. To maintain home insurance policy coverage, carriers are increasingly requiring verified, active risk mitigation.
As the first active wildfire defense system recognized by STAND Insurance, Frontline helps bridge the gap between risk and insurability. Proactive protection gives insurers the confidence needed to write, renew, and maintain policies in high-risk zones.
“Insurance is moving beyond ZIP codes toward a better understanding of property-level risk. Today, more sophisticated risk models can quantify how the steps a homeowner takes change a home’s likelihood of surviving a wildfire. As more insurers start to take this data into account, investing in active defense not only measurably improves a home’s ability to survive wildfire, but positions homeowners for where the insurance market is heading.”
— Harry Statter, Founder & CEO

Secure your property and protect your equity with Frontline.
Wildfire is unpredictable. Frontline isn’t. Take control of your property’s protection with an active defense system engineered to prevent fire before it starts.
*Automatic activation requires opting in on the Frontline App and having an active subscription. Wildfires are inherently unpredictable and dangerous. Use of the Frontline Wildfire Defense System is not a guarantee against loss of life or property from a wildfire.
© 2026 Frontline Wildfire Defense, Inc. All rights reserved.